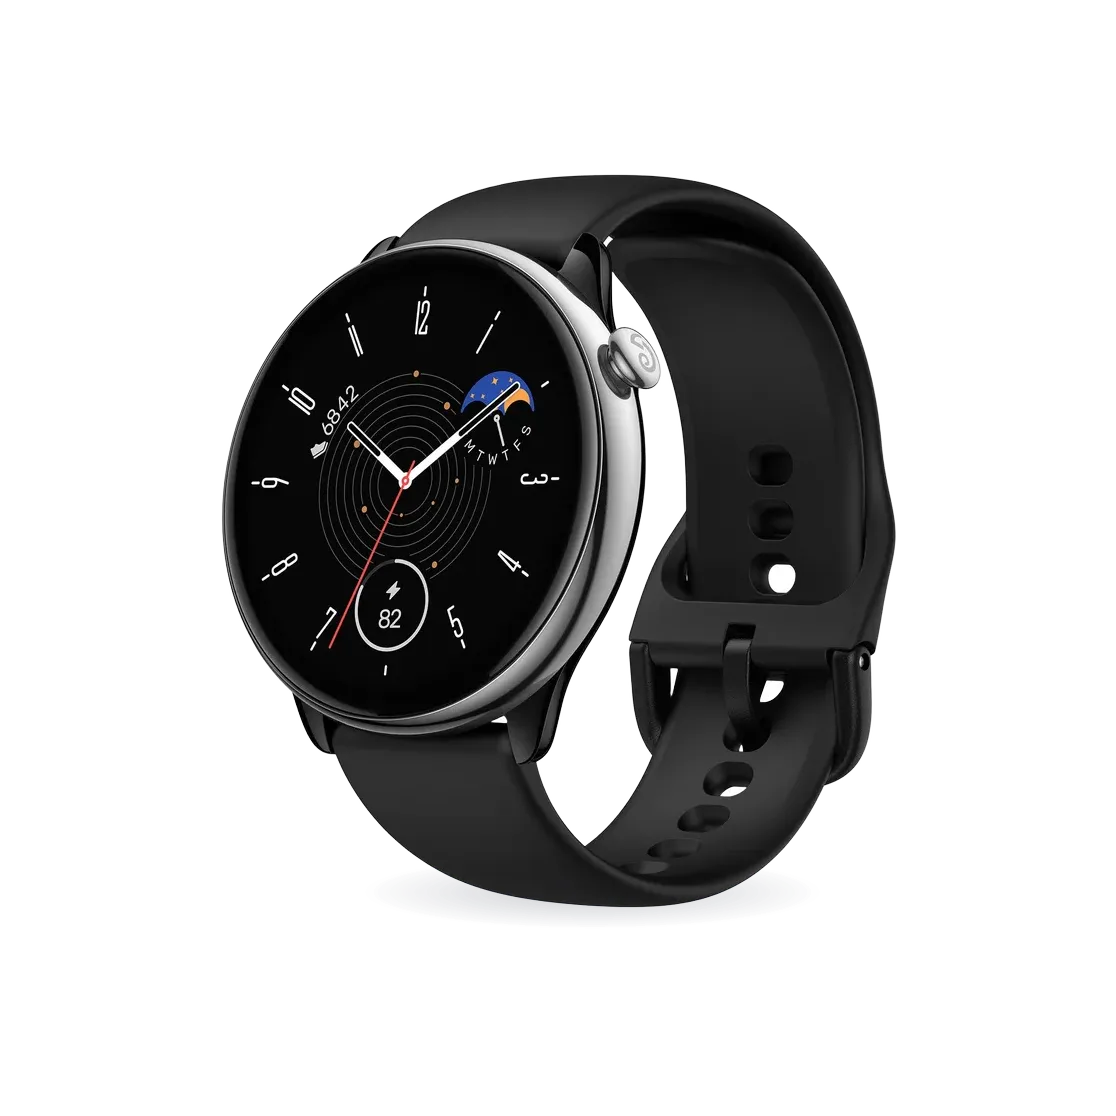
Amazfit GTR Mini
$119.99at amazfit.com
Covered by your benefits
- HSA
- Health FSA
Pay with your HSA or FSA card. No paperwork.
~$36 Est. tax saving
Pay with pre-tax HSA/FSA dollars on this $119.99 purchase
Amazfit GTR Mini is HSA/FSA eligible — pay with your benefits card at checkout.
Checked against common benefit plans. Your employer's plan may differ.
Benefit-maxxing tips
Use FSA first — it expires. Leave HSA to grow.
Similar products that are also covered
About this product
A slim smartwatch with a stainless steel case, 120+ sports modes, five satellite positioning systems, 24/7 heart rate, SpO2 and stress monitoring, and up to 14 days of battery life.
Quick facts
- Brand
- Amazfit
- Category
- Health & Wellness
- Concerns addressed
- Cardiovascular & Athletic Fitness, Biometric & Preventative Tracking
- IRS classification
- Qualified medical expense
- Caeli receipt vault
- Auto-saved for 7 years
- Sold by
- amazfit.com
Eligibility & Coverage FAQs
Written by Caeli's benefits team. If we haven't answered your question, the extension's in-app chat is staffed by humans.
Can I buy the Amazfit GTR Mini with my HSA or FSA?
Yes, when you buy it primarily to help diagnose, treat or prevent a specific condition, not for general fitness or wellness (IRS FAQ Q15). No letter is required: pay with your HSA or FSA card.
Do I need a doctor's note or LMN to buy the Amazfit GTR Mini?
No letter is required. What makes a wearable a medical expense is why you buy it: primarily for a specific condition. A clinician's recommendation, your symptoms, a diagnosis, abnormal test results or risk factors all count; a general wish to track or improve your health does not.
Does my wellness stipend (LSA) cover this?
Maybe — LSA coverage is set by your employer's plan, so it varies by person. Caeli reads your employer's LSA categories and tells you whether you can pay this way — often with no paperwork. If you have both an LSA and an HSA, Caeli steers you to spend the LSA first (it can expire) and protect the HSA (it compounds).