HSA, FSA, and LSA: What's the Difference (and What Can You Actually Buy)?
HSA, FSA, LSA — same pre-tax idea, very different rules. Here’s what each covers, when to use which, and how to stop leaving benefit dollars on the table in 2026
Every November, the same three letters show up on your benefits portal during open enrollment: HSA. FSA. LSA.
And every November, most people click past them as fast as possible — which is exactly how you end up paying out of pocket for Claritin, your kid’s allergy testing, and a $250 air purifier that your FSA would have covered without a second thought.
30-second summary: HSA vs FSA vs LSA
HSA (Health Savings Account)
- Tied to a qualifying high-deductible health plan (HDHP).
- 2026 HDHP minimum deductibles: $1,700 self-only / $3,400 family (IRS Rev. Proc. 2025-19).
- 2027 HDHP minimum deductibles: $1,750 self-only / $3,500 family, with out-of-pocket maximums of $8,700 self-only / $17,400 family (IRS Rev. Proc. 2026-24).
- 2026 contribution limits: $4,400 self-only / $8,750 family, plus $1,000 catch-up at 55+.
- 2027 contribution limits: $4,500 self-only / $9,000 family, catch-up stays $1,000 — confirmed by the IRS in May 2026.
- Covers IRS-qualified medical expenses (see IRS Pub. 969).
- Triple tax advantage: pre-tax contributions, tax-free growth, tax-free qualified withdrawals.
- Rolls over forever, portable if you leave your job, and can be invested.
- Power move: pay expenses out of pocket now, let the HSA grow for decades, reimburse yourself later with saved receipts.
FSA (Flexible Spending Account)
- Available if your employer offers it; no HDHP requirement.
- 2026 contribution limit: $3,400.
- 2027 contribution limit: not yet announced by the IRS. Expect the Revenue Procedure this October or November — we'll update this the moment it's official.
- Covers most of the same medical expenses as an HSA.
- Use-it-or-lose-it: leftover funds are generally forfeited at year-end.
- Some plans allow either (not both):
- Carryover up to $680, or
- 2.5-month grace period (to March 15).
- Full annual election is available on day one of the plan year.
- Separate Dependent Care FSA for childcare: 2026 limit $7,500 for couples filing jointly (per the One Big Beautiful Bill).
- 2027: stays at $7,500 (or $3,750 married filing separately) — a fixed dollar cap under 2025's tax law, not adjusted for inflation, so it carries forward without a fresh IRS announcement.
LSA (Lifestyle Spending Account)
- Funded entirely by your employer; you don’t elect contributions.
- Taxable to you: employer contributions show up on your W-2 like wages.
- Still effectively free money: a $1,000 LSA typically nets ~$650–$750 after tax.
- Eligible uses are employer-defined (no IRS list): often fitness, mental health, ergonomic/home office gear, family care, financial wellness, sometimes pet care.
- Usually does not roll over—use it within the plan year.
---
Caeli Spectrum
- Everyday medical (sunscreen, OTC pain meds, period products, bandages, thermometers)
- HSA: yes
- FSA: yes
- LSA: usually no
- Glasses, contacts, dental work, prescription copays
- HSA: yes
- FSA: yes
- LSA: usually no
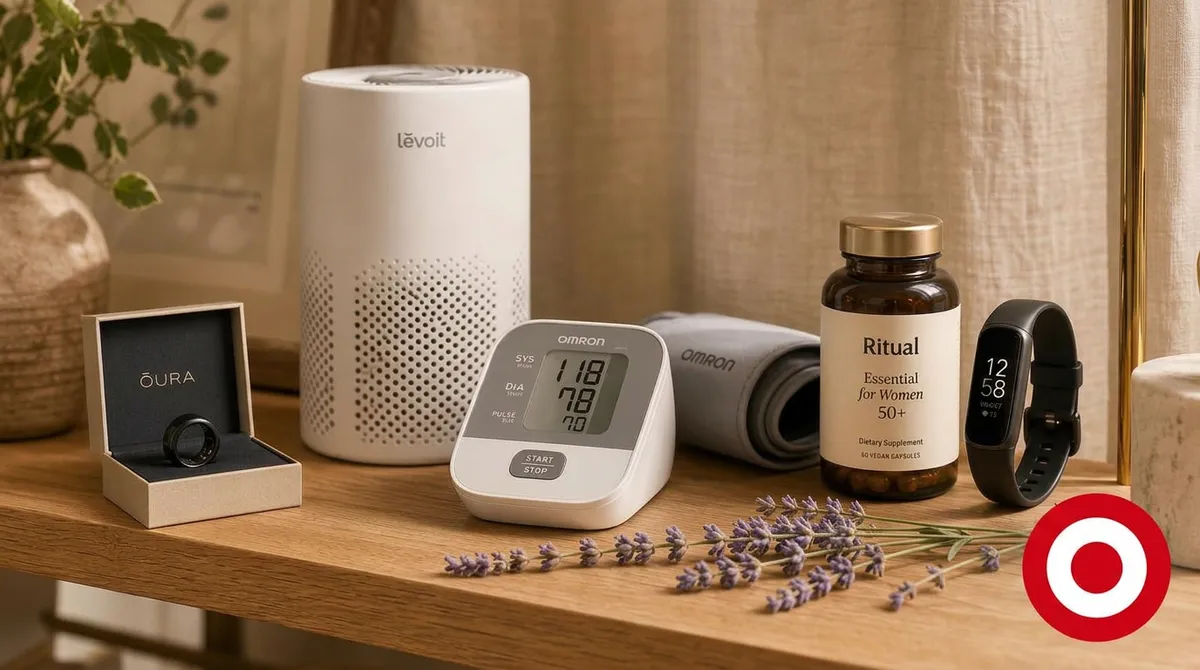
- Smart rings, high-end massage guns, light therapy devices
- HSA: yes, often with a Letter of Medical Necessity (LMN)
- FSA: yes, often with LMN
- LSA: depends on employer
- Air purifiers, hypoallergenic bedding, some supplements
- HSA: yes with LMN
- FSA: yes with LMN
- LSA: possibly, plan-dependent
- Gym memberships, yoga, meditation apps
- HSA: no (rare exceptions)
- FSA: no
- LSA: commonly yes
- Home office / ergonomic gear (chairs, standing desks)
- HSA: no
- FSA: no
- LSA: commonly yes
- Childcare, summer camp
- Dependent Care FSA: yes (separate from healthcare FSA)
- LSA: sometimes, depending on plan
- Pet care, financial coaching, therapy
- HSA: no (therapy is yes only when medically necessary and billed as healthcare, not as an LSA-style perk)
- FSA: no for pet care/financial coaching; yes for qualified mental health treatment as medical care
- LSA: often yes for all three, if employer allows
---
Best spending order if you have all three
- LSA first
- Taxable, often no rollover, and limited eligible list.
- Use it on things HSAs/FSAs don’t cover (gym, wellness apps, ergonomic gear, pet care, certain coaching).
- FSA next
- Use-it-or-lose-it risk.
- Spend down on predictable medical expenses during the year.
- HSA last
- Rolls over forever, can be invested, and is triple-tax-advantaged.
- If you can afford it, pay current medical costs out of pocket and let the HSA grow.
---
Common confusion points
- HSA + regular healthcare FSA?
- Generally no; that’s considered double-dipping.
- Exception: a Limited Purpose FSA (dental/vision only) can pair with an HSA and is often optimal.
- HSA + Dependent Care FSA?
- Yes. One is for medical, the other for childcare.
- Do funds roll over?
- HSA: yes, indefinitely.
- FSA: maybe up to $680 or a 2.5‑month grace period, depending on plan.
- LSA: usually no.
- Why is LSA taxable but HSA isn’t?
- HSA: funded with pre-tax payroll dollars; never counted as income.
- LSA: employer adds money on top of your pay; IRS treats it as wages.
- Can you invest FSA or LSA balances?
- No. Only HSAs can be invested.
- If you leave your job:
- HSA: yours to keep.
- FSA: leftover funds usually forfeited (with limited COBRA options).
- LSA: forfeited.
---