Open Enrollment for New Parents: A Benefits Expert on What to Change After Baby (2027)
Add your baby within 30 days, pick their plan on purpose, and use your next open enrollment for life insurance, a will and a dependent care FSA.
Nobody hands you a benefits checklist at the hospital. Between feedings and paperwork, there's a deadline most new parents don't know exists: you usually have 30 days to add your baby to your health insurance.
Here's the fast answer: in your first year as a parent, add your baby to a health plan within 30 days of the birth, decide which parent's plan they go on before the birth, and at your next open enrollment, add life insurance, a basic will that names a guardian, a dependent care FSA if daycare is coming, and a fresh look at the short-term disability and hospital plans you bought for the birth.
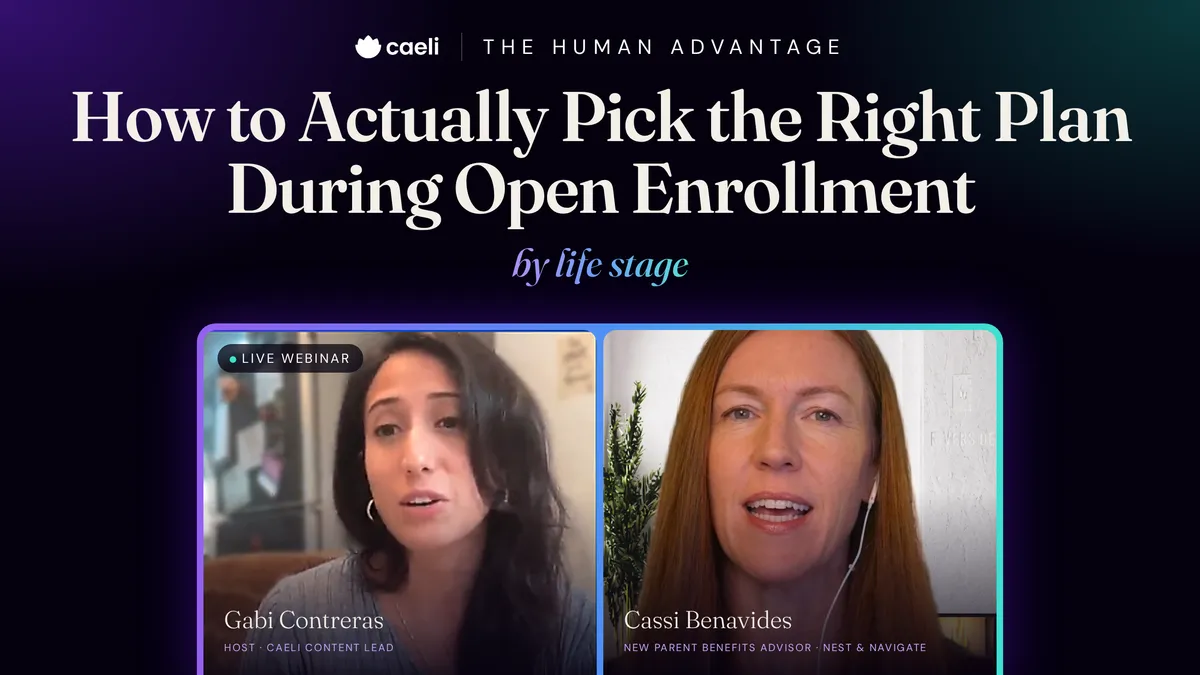
To walk through the baby years, we sat down with Cassi Benavides, founder of Nest & Navigate, where she gives new families white-glove, one-on-one guidance as their personal benefits advisor. Cassi has spent 13 years in HR and benefits management, and she has navigated these same decisions as a mom herself. Prefer to watch? Here's Cassi's breakdown of the birth and baby years, or catch the full conversation on YouTube.
Your 30-second cheat sheet for the baby years
Within 30 days of the birth
- Add your baby to your health plan.
- Update your beneficiaries, without naming the baby directly.
At your next open enrollment
- Life insurance sized to your family's needs.
- A basic will that names a guardian.
- A dependent care FSA if your child will be in daycare.
- Short-term disability and hospital plans: keep them if another baby is coming, consider dropping them if not.
Any time
- Your EAP for therapy, childcare referrals and more.
TL;DR: The 30-day window comes first, then life insurance, a will and childcare dollars at your next open enrollment.
How long do you have to add a newborn to your insurance?
At least 30 days. Employer plans must give you a 30-day window after a birth or adoption to request enrollment, and when you enroll in time, coverage has to start as of the date of birth. Some plans give you longer, but don't count on it.
Cassi has seen what happens when you miss it. One family reached out months after their baby was born, and the baby couldn't be added until open enrollment. Put the deadline in your phone before your due date, or ask someone you trust to remind you.
TL;DR: Request enrollment within 30 days of the birth, and coverage will date back to the day your baby was born.
Which parent's plan should your baby go on?
Decide before the birth, Cassi says, because you don't want to be building a spreadsheet with a crying newborn.
"You don't wanna be at home with a newborn crying, trying to do this spreadsheet."
Start with the monthly premium for family coverage at each job. Before kids, it's often cheapest for each parent to stay on their own plan. After the baby, putting the whole family on one plan sometimes wins on cost, and it's easier to manage. Two plans means two logins, two doctor networks and two sets of rules while you're searching for a pediatrician.
"I find it the hardest scenario for the mental load of the mom when the mom and the baby are on different insurance plans."
TL;DR: Compare family premiums at both jobs, then weigh the mental load of juggling two plans.
How much life insurance do new parents need?
Cassi's rule of thumb: how much does your family depend on your income, and what would it take to keep a roof over their heads until your kids are grown? Check how much life insurance your employer already provides, then buy supplemental coverage to close the gap.
"As soon as you become a parent, the most important thing to you is making sure your child will be taken care of."
When you set beneficiaries, don't list your baby directly. Insurers generally can't pay a minor, which can mean court involvement and delays. Our guide to naming a child as a life insurance beneficiary explains what to do instead.
TL;DR: Size life insurance to your family's living costs until your kids are grown, and don't name a minor as beneficiary.
Do you need a will as soon as your baby is born?
Cassi says yes, at least a basic one, because the most important thing it does is name a guardian. She remembers scrambling to get one after her son was born. Basic wills are often bundled into other benefits, like your life insurance, your 401(k) provider or a group legal plan, so check before paying a lawyer. Our guide to perks hiding in your benefits covers legal plans.
TL;DR: Get a basic will that names a guardian, and check whether your benefits already include one.
What is an EAP, and why should new parents use it?
An Employee Assistance Program is one of the most underused benefits Cassi sees. EAPs are free and confidential, and many cover short-term counseling, financial planning and help finding care. Cassi says household members can usually use it too, so you and your partner could each see a therapist after the baby arrives.
"I'm gonna guarantee there's at least one thing that would be valuable to you."
Read our full guide to using your EAP as a new parent.
TL;DR: Your EAP likely offers free counseling and childcare help, so look it up before you need it.
Should you add a dependent care FSA?
If your baby will be in daycare, almost certainly. A dependent care FSA lets you pay for childcare with pre-tax money, and the household limit is $7,500 for 2027 if your employer has adopted the higher cap. Preschool and nursery school count as care under IRS rules. It won't cover all of childcare, but it saves you taxes on part of it. Our dependent care FSA guide runs the math.
Keep funding your health FSA or HSA too. Cassi's warning: once you have a child, you'll be using your insurance a lot more. Caeli flags eligible items on Amazon, Target and CVS before you pay, from infant thermometers to first aid kits, and at checkout, eligible items go on your FSA or HSA card while everything else lands on your backup card.
TL;DR: Add a dependent care FSA for daycare, and keep your health account funded for a year of sick days.
Should you keep short-term disability and hospital plans after the baby?
Revisit them at your next open enrollment. Cassi's rule: keep them if you're planning another baby, since they may have waiting periods, and consider dropping them if you're done.
TL;DR: Keep birth-related coverage if another baby is in the plan, and drop it if not.
Caeli Pro-Tip: The first year with a baby means a lot of small health purchases: thermometers, nasal aspirators, saline, first aid kits. Install Caeli and each eligible item gets flagged before you pay, so those 2am pharmacy runs come out of your HSA or FSA instead of your paycheck. Itemized receipts are paired with any LMN in one record. Install Caeli and let your benefits handle the small stuff.
Frequently asked questions
What happens if I miss the 30-day window to add my newborn to insurance?
You may have to wait until your next open enrollment. Some plans allow longer than 30 days, so call HR right away if you've missed it.
Does newborn coverage start on the date of birth?
Yes, for employer plans, when you request enrollment within the special enrollment window, coverage starts as of the birth date.
Should my baby be on my plan or my partner's plan?
Compare the family premiums at both jobs, then consider the networks. Many parents find one shared plan easier to manage.
Can I use my dependent care FSA for preschool in 2027?
Yes. The IRS counts preschool and nursery school as care. Kindergarten and school tuition don't count.
Can my partner use my EAP for therapy after the baby is born?
Often, yes. Many EAPs extend to household members. Check your plan's details.
Should I keep short-term disability after having a baby?
Keep it if you're planning another pregnancy, because it may have waiting periods. Consider dropping it if you're not.
The bottom line
The baby years run on very little sleep, so make the big decisions early. Pick the baby's plan before the birth, get enrollment in within 30 days, and use your next open enrollment to lock in life insurance, a will and childcare dollars. Want help with your family's plan? Book a free consultation with Cassi, or read our full guide to choosing a health plan for your life stage.
This article is for education only and isn't tax, legal or financial advice. Plan rules vary by employer and state.