How to Choose a Health Plan: A Benefits Expert's Decision Tree for Open Enrollment
Seven health plans, one choice. A benefits expert's process of elimination for choosing a health plan at open enrollment, step by step.
Open enrollment hands you a stack of plans, a wall of acronyms and a few weeks to decide. If you and your partner both work, you could be comparing seven or eight options at once.
Here's the fast answer: to choose a health plan at open enrollment, use process of elimination. List every plan you can get, cross off any that don't cover your must-have doctors, cross off the highest out-of-pocket maximums if a big medical cost is coming, cross off plans that don't cover your prescriptions well, then break the tie with your monthly budget, HMO versus PPO, and any money your employer adds to an HSA or HRA.
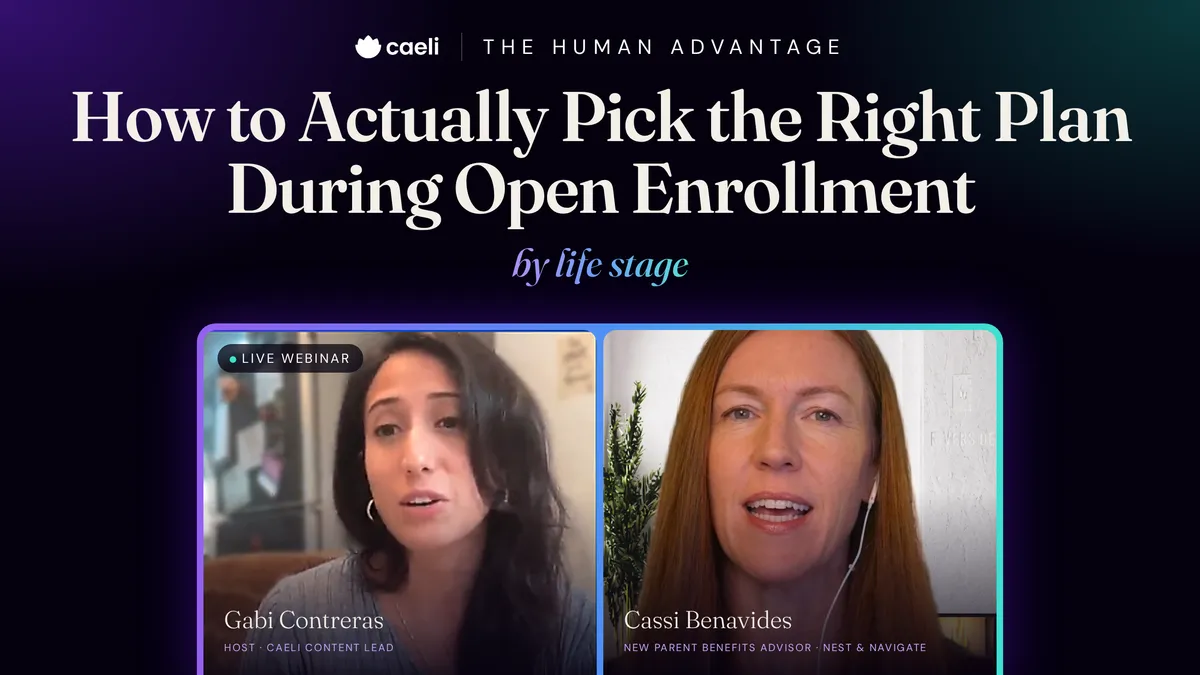
That's the decision tree Cassi Benavides walked us through. Cassi is the founder of Nest & Navigate, where she gives new families white-glove, one-on-one guidance as their personal benefits advisor, and she has spent 13 years in HR and benefits management. Even she nearly got it wrong: comparing seven plans before her son's birth, she almost picked one that would have cost $3,000 more. You can watch the full conversation on YouTube.
Your 30-second cheat sheet: Cassi's decision tree
Cross off
- Plans that don't cover your must-have doctor.
- The highest out-of-pocket maximums, if a birth or surgery is coming.
- Plans where your prescriptions are missing or in the priciest tier.
Then break the tie with
- Your monthly budget
- HMO or PPO
- Employer HSA or HRA money
Before you enroll
- Save at least your deductible in your bank account, HSA or FSA.
TL;DR: Eliminate plans by doctor, big planned costs and prescriptions, then let budget, network and employer money decide.
Why use process of elimination?
Because seven or eight plans is too many to compare all at once. If you and your partner both work, you might be choosing across both employers.
"I like to use process of elimination just to decrease that overwhelm."
Cassi treats it like a multiple-choice test. You don't need to pick the best plan right away. You just need to rule out the wrong ones.
Start by listing every plan available to your household, with its monthly premium, deductible and out-of-pocket maximum.
TL;DR: List every plan across both jobs, then start crossing off instead of comparing everything at once.
Step 1: Do you have a must-have doctor?
This is Cassi's first question. Maybe you see a specialist for a chronic condition. Maybe you just love your doctor. Cassi has seen hers for 10 years and plans to stay until she retires.
Check each plan's network for your doctor, then cross off any plan where you couldn't see them.
TL;DR: If a plan doesn't cover a doctor you need or love, cross it off first.
Step 2: Is a big medical cost coming?
Think about the next 12 months. A birth, a knee replacement or another planned surgery changes the math. If one is coming, look at each plan's out-of-pocket maximum, the most you'll pay for covered care in a year, and cross off the plans with the highest caps.
If nothing big is planned, the deductible usually matters more, because that's what you'll pay for everyday care before insurance shares the cost. That's when a higher deductible can be a good thing: you pay less in premiums every month, and if you rarely use care, you come out ahead.
TL;DR: With a big planned cost, cross off the highest out-of-pocket maximums. Without one, a higher deductible can save you money.
Step 3: What about your prescriptions?
Plans group drugs into tiers, and the same medication can cost very different amounts depending on the tier. Look up each prescription you take, check whether it's covered and which tier it's in, and cross off plans where it's missing or most expensive.
TL;DR: Check every prescription's coverage and tier, and cross off plans that price them highest.
Step 4: How do you break the tie?
Whatever's left, Cassi uses three tiebreakers.
- Your monthly budget. Does the premium fit? If nothing left fits, start over and loosen one of your must-haves.
- HMO or PPO. An HMO keeps you in a network and usually routes you through your primary care doctor, for a lower premium. A PPO lets you go out of network, for a higher premium. Cassi says this is the most popular tiebreaker, and some people feel strongly either way.
- Employer money. If your employer adds money to a health reimbursement account (HRA) or an HSA, subtract it from what you'd owe under the deductible. Cassi says HRAs are getting more common, often paired with higher deductibles.
TL;DR: Break the tie with budget, network type and any employer HSA or HRA money.
How much should you have saved before you enroll?
At least your deductible, Cassi says, in your bank account, HSA or FSA. If you need an X-ray or a procedure, you'll usually pay the deductible before insurance starts paying.
If you choose a high-deductible plan with an HSA, the account can do a lot of work. For 2027, a plan needs a deductible of at least $1,750 for self-only or $3,500 for family coverage to qualify, and you can contribute up to $4,500 or $9,000. In the 22% federal tax bracket, $1,000 in an HSA or FSA saves $220 in federal income tax alone, and payroll contributions generally skip Social Security and Medicare taxes too.
Once your money is set aside, use it. Caeli flags eligible items on Amazon, Target and CVS before you pay, and at checkout, eligible items go on your FSA or HSA card while everything else lands on your backup card.
TL;DR: Keep your deductible saved, and if you choose an HSA, fund it, because every dollar skips taxes.
Caeli Pro-Tip: Chose a high-deductible plan to save on premiums? Put the savings into your HSA, then spend it on things you'd buy anyway. For dual-purpose items like a Levoit air purifier for asthma, Caeli runs a chat-based telehealth consultation right inside checkout, under 3 minutes, no doctor's visit required, and a licensed clinician issues the LMN within 24 hours. Install Caeli and make your deductible dollars go further.
Frequently asked questions
How do I choose between health plans during open enrollment in 2027?
Use process of elimination: cross off plans that don't cover your doctors, then the highest out-of-pocket maximums if a big cost is coming, then plans that price your prescriptions highest. Break ties with budget, network type and employer money.
When is a higher deductible a good thing?
When you don't expect big medical costs. You pay lower premiums every month, and an HSA lets you save the difference pre-tax.
Should I compare the deductible or the out-of-pocket max?
If a birth or surgery is planned, compare out-of-pocket maximums. Otherwise, the deductible and premium usually matter more.
What's the difference between an HMO and a PPO?
An HMO keeps you in a network and usually requires your primary care doctor first, for lower premiums. A PPO lets you see out-of-network providers, for higher premiums.
What is an HRA?
A health reimbursement account is employer-funded money for medical costs. It's often paired with a higher-deductible plan, so subtract it from what you'd owe.
How much money should I have saved for my deductible?
Cassi recommends at least the full deductible of the plan you choose, in savings, an HSA or an FSA.
The bottom line
You don't need a perfect spreadsheet to pick a good plan. Rule out the wrong ones, break the tie, and make sure your deductible is covered. Want Cassi to walk through your options? Book a free consultation with Cassi, or read our full guide to choosing a health plan for your life stage.
This article is for education only and isn't tax, legal or financial advice. Plan rules vary by employer and state.